Business restructuring after a crisis should not begin with a list of expenses to cut. It should begin with the constraint the crisis exposed. Stabilize enough cash and operating capacity to make deliberate decisions, identify what now prevents the business from creating and collecting value, protect the capabilities closest to that value, and then change the parts of the operating model that no longer fit.
That distinction matters. A business can cut costs quickly and still make itself weaker. It can keep every employee and still preserve a model that no longer works. It can buy new software, launch new marketing, or reorganize reporting lines and accomplish little because none of those moves addressed the binding constraint.
If you are still preparing for disruption or trying to keep critical operations running during one, start with our business resilience framework. This guide owns the next job: what to do when a crisis reveals that the underlying business structure itself needs to change.
TL;DR: stabilize enough to make good decisions
- Protect enough runway to avoid making every decision under immediate cash pressure.
- Diagnose the binding constraint before choosing a tactic such as layoffs, new marketing, outsourcing, automation, or expansion.
- Protect the customer outcome and capability that still make the business worth keeping.
- Reorganize costs, people, vendors, technology, and processes around that core instead of around the old org chart.
- Validate the restructured model with break-even math, capacity evidence, customer behavior, and small reversible tests before making every change permanent.
- Sequence the transition so the restructuring does not create a second crisis.
- Measure the business consequence you intended to change, then reallocate based on evidence.
What business restructuring actually means
Business restructuring is the deliberate redesign of a company’s financial, operational, organizational, or commercial structure so the business can operate sustainably under a changed reality. The change might involve the cost base, revenue mix, staffing model, vendor relationships, ownership of work, processes, technology, pricing, delivery model, customer focus, or some combination of them.
Restructuring is broader than “cutting costs,” and it is not automatically a legal or bankruptcy process. In the United States, Chapter 11 is a formal court-supervised reorganization process, with special provisions that may apply to eligible small-business debtors. If your situation involves insolvency, creditor rights, bankruptcy, taxes, entity structure, or material employment and contract changes, bring qualified legal and financial professionals into the decision. U.S. Courts explains the Chapter 11 framework and small-business provisions here.
| Restructuring area | Primary question | Examples of evidence |
|---|---|---|
| Financial | Can the business fund itself and produce acceptable economics? | Cash runway, gross or contribution margin, break-even, receivables, debt obligations |
| Operational | Can the business reliably deliver what customers are paying for? | Capacity, cycle time, errors, rework, fulfillment, bottlenecks, dependencies |
| Organizational | Who should own the capabilities the new model requires? | Decision rights, role load, founder dependence, specialist needs, continuity |
| Commercial | Is the offer still valuable to the right customer at workable economics? | Demand, win rate, pricing, objections, retention, customer profitability |
| Technology and systems | Which systems enable the model, and which merely automate old problems? | Adoption, maintenance burden, integration failures, manual exceptions, error risk |
When does a business need restructuring?
Not every rough quarter requires a company-wide restructure. The better question is whether the crisis exposed a temporary disruption or a structural mismatch.
- Cash is tight because timing changed: collections slowed, a major customer paid late, or an event temporarily interrupted operations. That may require stabilization more than redesign.
- The economics no longer work: the business can sell, but the margin does not support delivery, overhead, or the capacity required to grow.
- Demand changed: the old customer, offer, channel, or buying trigger is no longer producing enough profitable demand.
- Capacity is the constraint: demand exists, but delivery, staffing, founder dependence, scheduling, or systems prevent the business from serving it profitably.
- A dependency became unacceptable: one supplier, platform, employee, process, owner, or system has become a single point of failure.
- The company is preserving activity instead of value: teams remain busy, but the work does not improve customer outcomes, cash generation, margin, retention, throughput, or another meaningful business consequence.
Scope Design’s broader business strategy framework starts with the same discipline: begin with the decision and business outcome, make the constraints and alternatives visible, and then choose the resources and tactics that fit.
Use the Scope Design RECOVER Restructuring Loop
We use a constraint-first sequence for crisis recovery because downstream fixes are unreliable when the upstream diagnosis is wrong. The RECOVER Restructuring Loop turns that reasoning into seven steps:
- Runway: buy enough decision time.
- Expose the constraint: identify what is actually blocking the desired outcome.
- Choose the core: protect the customer outcome and capability worth preserving.
- Organize resources: align people, vendors, tools, costs, and ownership around the core.
- Validate the new model: test economics and operating assumptions before locking them in.
- Execute the transition: sequence change without breaking critical delivery.
- Review and reallocate: measure the consequence, learn, and move resources again.
R — Runway: buy decision time
Restructuring under panic is expensive because everything looks urgent. Start by making the cash picture visible enough to know what can wait, what cannot, and how much room the business has to test alternatives.
- Map expected cash receipts and obligations by date, not just by monthly total.
- Separate expenses required to keep critical value delivery working from costs that belong to the old model.
- Review receivables, supplier terms, recurring commitments, debt covenants, tax obligations, insurance, and contractual constraints with the appropriate professionals.
- Create more than one scenario when timing or demand is genuinely uncertain.
- Define the minimum cash and capacity required to keep customer commitments safe during the transition.
The U.S. Small Business Administration’s current resilience guidance emphasizes essential operations, dependencies, financial readiness, cash flow, emergency funding, and loss reduction. Its disaster programs are specific to eligible declared-disaster circumstances; they are not a universal source of restructuring capital for any struggling business. See the SBA’s emergency preparedness guidance and Business Resilience Guide announcement.
E — Expose the binding constraint
Do not accept the diagnosis embedded in the requested tactic. “Cut payroll,” “launch ads,” “hire a salesperson,” “move remote,” “automate this,” and “rebuild the website” are proposed interventions. They are not proof of the problem.
Write the decision before you write the solution:
We are deciding whether to change [part of the business model] for [customer or operation] to improve [business consequence], compared with [real alternatives], within [cash, capacity, legal, time, or risk constraints].
Then look for the constraint. Is the business short of demand, or is demand unprofitable? Is sales weak, or is delivery capacity forcing the company to reject good work? Is payroll the problem, or is the real problem that too many roles are organized around work customers no longer value? Is the website broken, or is lead follow-up so slow that better conversion would simply feed a bad handoff?
C — Choose the core capability and customer outcome to protect
A crisis can make every expense look equally suspicious. They are not equally important. Identify the customer outcome that still has economic value and the capabilities required to produce it reliably.
For one business, the core may be trusted expert judgment. For another, it may be fast field service, a proprietary dataset, a difficult fabrication process, a distribution relationship, a recurring customer workflow, or a reputation built over decades. The point is not to preserve everything around the capability. The point is to avoid cutting the capability itself while trying to reduce the cost of supporting it.
O — Organize resources around the core
Now redesign ownership. Which capabilities belong inside the business? Which can be provided by a specialist, contractor, partner, managed service, or temporary project team? Which work should disappear entirely?
Do not make this an ideological “employees versus outsourcing” debate. Keep ownership of strategy, customer knowledge, standards, decision rights, and critical intellectual property where the business needs them. Use external capacity where variability, specialization, speed, or economics justify it. Our in-house vs. outsourcing decision framework goes deeper on that tradeoff.
V — Validate the new model before making every change permanent
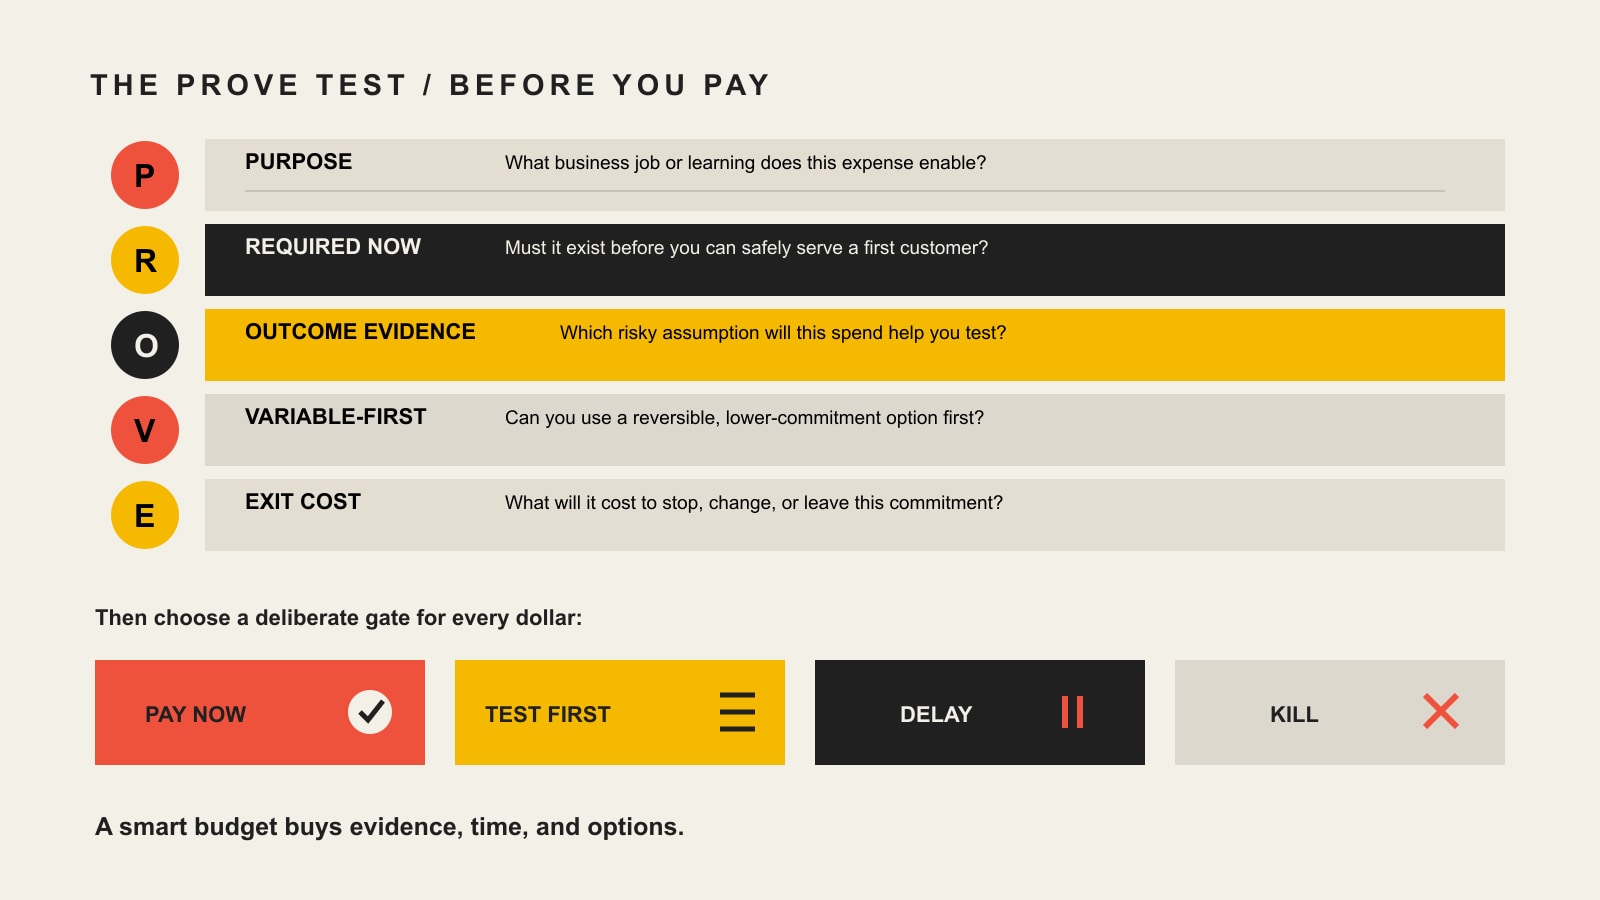
A restructuring plan is still a collection of assumptions until customers, operations, and economics test it. Validate at the smallest scale that can change the decision.
- Test a revised offer with real prospects before rebuilding the entire sales system around it.
- Pilot a new delivery workflow with a narrow customer group before forcing it across every account.
- Use a project or managed-service arrangement to test external capability before removing internal knowledge you may need.
- Model capacity and margin before celebrating a lower fixed-cost number.
- Define the evidence that would cause you to continue, revise, or stop the change.
Break-even analysis is useful here because it forces the economics into the open. The SBA expresses unit break-even as Fixed Costs ÷ (Price − Variable Costs). A restructured business with lower overhead can still be fragile if contribution margin is poor or the required sales volume is unrealistic. The SBA’s break-even guide explains the calculation and its assumptions.
E — Execute the transition without creating a second crisis
Good restructuring decisions can still fail through bad sequencing. Map dependencies before moving pieces. If a role is changing, who owns the work during the transition? If a system is being replaced, what happens to historical data and exceptions? If an offer is being retired, how will existing customers be served? If a supplier relationship changes, what is the fallback if the replacement fails?
- Name an owner for each material change.
- Define the trigger or evidence that allows the next change to proceed.
- Protect customer commitments and compliance obligations during migration.
- Communicate what is changing, what is not, and where decisions now live.
- Preserve a rollback or fallback path when the downside of failure is meaningful.
R — Review the evidence and reallocate
Do not let the restructuring “succeed” because the project plan finished. Measure the business consequence it was meant to change.
If the goal was stronger economics, watch cash generation, gross or contribution margin, retained revenue, or another measure close to money. If the constraint was capacity, measure throughput, cycle time, backlog, service quality, and the cost of exceptions. If the problem was a weak offer, measure qualified opportunity rate, win rate, discount pressure, retention, and delivery margin.
Then add a quality check so one metric cannot declare victory while the business loses. Revenue can grow while margin collapses. Leads can rise while close rate falls. Automation can reduce manual steps while creating a brittle dependency. A smaller payroll can improve a spreadsheet while destroying delivery capacity.
What should you cut, protect, or change first?
| Decision | Use it when | Question to answer |
|---|---|---|
| Protect | The resource is causally tied to a valuable customer outcome, scarce capability, proof, compliance, or critical continuity. | If this disappears, what valuable outcome becomes harder or impossible to deliver? |
| Cut | The cost supports work the new model no longer needs and removing it does not create a larger hidden cost. | What business consequence gets worse if we stop paying for this? |
| Test or change | The resource could matter, but its value depends on an assumption that has not been proved. | What small experiment would tell us whether this deserves more resources? |
| Sequence later | The change may be useful but depends on a more important constraint being fixed first. | What must be true before this change can create value? |
This is why percentage cuts across every department are so tempting and so dangerous. They are simple to administer. They also assume every cost has the same relationship to value creation, which is rarely true.
Rebuild the financial model before you call the restructuring done
A smaller cost base is not the same thing as a healthy business. Rebuild the model around the economics you actually expect to operate with:
- Revenue by offer, customer type, channel, and recurrence.
- Direct or variable cost required to produce each revenue stream.
- Contribution margin and the fixed capacity needed to support it.
- Cash timing: when revenue is booked versus when cash is actually received.
- Working-capital needs created by inventory, deposits, supplier terms, payroll, or project timing.
- Customer concentration and other dependencies that could recreate the crisis.
- Break-even volume under conservative, expected, and stronger-demand scenarios.
The goal is not a prettier forecast. It is a model that makes the tradeoffs visible enough to decide what the company can safely promise, fund, and scale.
Restructure work around capability, not payroll labels
Headcount is easy to see because it sits on the income statement. Capability is harder to see because it is spread across people, relationships, documented processes, tacit knowledge, tools, and decision rights.
Before changing staffing, map the work required by the new operating model. Which work is continuous? Which is bursty? Which requires deep context? Which requires rare specialist expertise? Which must remain close to the customer? Which carries material security, compliance, or intellectual-property risk?
Then choose the resource model. Sometimes that means fewer roles. Sometimes it means different roles. Sometimes it means a smaller internal team with specialist external capacity. Sometimes the right answer is keeping a capability in-house because coordination or context matters more than an apparent hourly-rate saving.
If the market changed, restructure the offer too
A company with a demand problem can waste months treating it as a cost problem. If the crisis changed what buyers value, what they can afford, how they buy, or which alternatives they compare, the old offer may need to change with the operating model.
Review the product or service, price, delivery process, proof, promotion, and channel together. Our 7 Ps product strategy audit is useful here because it forces the parts of the offer to fit one another instead of assuming more promotion will rescue a weak exchange.
Competitive intelligence is useful when it reveals tradeoffs rather than just tactics to copy. Which competitor advantage depends on scale, capital, distribution, reputation, data, or systems you do not possess? Which customer do competitors neglect? Which part of a competitor’s model would destroy your margin or capacity if you copied it? Those are restructuring questions because they determine what the new model should refuse to become.
Technology can remove friction—or automate the wrong damn process
Crises often create pressure to automate quickly. Automation can reduce repetitive work and improve consistency, but it can also make a bad process faster and harder to understand.
Map the workflow first: inputs, decisions, owners, exceptions, outputs, customer consequences, and failure modes. Then decide which steps should disappear, which should remain judgment-heavy, and which are stable enough to automate. If the process is still changing every week because the operating model is unresolved, the automation is probably early.
Crisis recovery, resilience, continuity, restructuring, and formal reorganization are different jobs
| Job | Primary question | Typical time focus |
|---|---|---|
| Crisis response | What must we do now to protect people, customers, cash, and critical operations? | During the event |
| Business resilience | How do we reduce fragility and preserve important outcomes when disruption occurs? | Before, during, and after disruption |
| Business continuity | How quickly must critical processes recover, and how much interruption or data loss is tolerable? | Recovery of critical functions |
| Business restructuring | Which parts of the business model must change because the old assumptions no longer hold? | Structural recovery and redesign |
| Formal legal reorganization | How are debts, creditor rights, contracts, and legal obligations reorganized under applicable law? | Formal legal/financial process |
Ready.gov’s business continuity planning materials tie continuity planning to a Business Impact Analysis and recovery objectives for time and data. That is useful for restoring critical processes. Restructuring asks a different question: should this process, cost structure, offer, or dependency be preserved in its old form at all? See the Ready.gov business continuity plan template.
A Scope Design example: foundation first, features second
A long-established specialty auction business came to Scope Design asking for a new website and new features. The visible site was clearly old and difficult to use, so a redesign proposal would have looked completely reasonable.
Discovery exposed a larger system. The website sat on top of legacy software, disconnected auction and inventory data, broken forms, unreliable commerce, manual invoicing, email-delivery problems, shipping workflows, and years of historical information.
The requested deliverable was “new website.” The actual strategic decision was how to modernize a business-critical operating system without pretending a prettier interface would repair the foundation underneath it. The sequence changed to foundation first, features second.
That is the same mistake crisis restructuring needs to avoid. A visible problem is not always the binding constraint. Treat the requested fix as evidence, then diagnose the system behind it.
A practical 90-day business restructuring plan
Ninety days is a useful execution cadence, not a promise that a turnaround will be finished in three months. Complex debt, legal, workforce, technology, property, or supply-chain changes may take much longer.
Days 1–14: stabilize and map the system
- Build the short-horizon cash picture.
- List critical customer commitments and operational dependencies.
- Define the business outcome that needs to change.
- Identify the leading candidate constraint and the evidence for it.
- Freeze irreversible changes that are not required for immediate safety, compliance, or survival.
Days 15–30: choose the core and create the stop list
- Name the customer, problem, offer, and capability the new model will prioritize.
- Identify work, costs, products, channels, and commitments that do not fit.
- Separate “protect,” “cut,” “test/change,” and “sequence later.”
- Document legal, contractual, employment, tax, lender, and supplier questions that require specialist review.
Days 31–60: redesign economics and capacity
- Rebuild revenue, margin, break-even, and cash assumptions.
- Redesign ownership of critical capabilities.
- Test revised offers, processes, staffing/vendor models, or technology at a reversible scale.
- Define the evidence required before committing more resources.
Days 61–90: execute, measure, and reallocate
- Sequence approved changes by dependency.
- Assign decision owners and transition responsibilities.
- Track the primary business consequence plus a small set of leading signals.
- Review failures and exceptions rather than averaging them away.
- Scale what is working, revise what is uncertain, and stop what the evidence no longer supports.
Common business restructuring mistakes
- Cutting by line item instead of business consequence. Equal percentage cuts are easy to explain and often blind to which capabilities create value.
- Treating a demand problem as a marketing-execution problem. More traffic will not rescue an offer buyers no longer want at workable economics.
- Treating a margin problem as a pure cost problem. Lower overhead cannot fix poor contribution margin indefinitely.
- Automating before the workflow is defined. Software can harden a process that should have been removed.
- Making every change permanent immediately. Reversible tests are cheaper than betting the company on a spreadsheet.
- Measuring activity instead of the intended business consequence. A completed restructuring project is not proof that the business is healthier.
- Ignoring second-order consequences. A cut can damage customer experience, compliance, delivery capacity, institutional knowledge, or future revenue.
- Ignoring legal and financial boundaries. Debt, insolvency, employment, tax, creditor, and contractual decisions are not generic management advice.
- Trying to recreate the pre-crisis company exactly. Recovery should preserve what still creates value, not every assumption that existed before the disruption.
Business restructuring FAQ
What does restructuring a business mean?
Business restructuring means deliberately changing the company’s financial, operational, organizational, or commercial structure to improve viability under current conditions. It can involve costs, staffing, vendors, processes, technology, pricing, offers, channels, financing, or delivery. It does not automatically mean bankruptcy or layoffs.
How do I restructure my business?
Start by stabilizing enough cash and operating capacity to make deliberate decisions. Define the business outcome, diagnose the binding constraint, choose the customer outcome and capability worth protecting, reorganize resources around that core, validate the new economics and operating assumptions, sequence the transition, and then review evidence before reallocating again.
What are the main types of business restructuring?
Labels vary by source and profession, but a practical small-business view is financial restructuring, operational restructuring, organizational restructuring, and commercial restructuring. Formal legal reorganization is a separate specialist area with jurisdiction-specific rules.
Can you give an example of business restructuring?
A service business might discover that demand is healthy but delivery depends on one founder who approves every project. The restructure may involve narrowing the offer, documenting standards, changing role ownership, moving specialist burst work to outside capacity, and rebuilding pricing around the true delivery cost. The goal is not “fewer people.” It is a model that can deliver the chosen customer outcome without the founder remaining the bottleneck.
Does restructuring always mean layoffs?
No. Workforce changes can be part of restructuring, but restructuring can also involve pricing, product mix, vendor strategy, process redesign, technology, financing, facilities, decision rights, or customer focus. When employment changes are contemplated, use qualified HR and legal guidance for the applicable jurisdiction.
What is the difference between a business turnaround and restructuring?
A turnaround is the broader effort to restore a struggling business to acceptable performance. Restructuring is one possible part of that effort: changing the underlying financial, operating, organizational, or commercial structure. A turnaround can also include temporary stabilization measures that are not structural changes.
How much does business restructuring cost?
There is no useful universal benchmark. Cost depends on what must change. Separate advisory and professional fees, severance or workforce-transition costs where applicable, software and migration costs, contract termination or renegotiation costs, financing costs, lost productivity during the transition, and the working capital required to operate while changes take effect. Formal legal or debt restructuring can add substantial specialist costs and should be scoped professionally.
What is the difference between resilience and restructuring?
Resilience is the ability to preserve important outcomes and adapt through disruption. Restructuring changes the underlying model when the old assumptions no longer fit. A resilience plan may help you discover that a dependency is unacceptable; restructuring is the work of redesigning around that discovery.
When should I involve an attorney, CPA, lender, or restructuring professional?
Bring specialists in when decisions involve insolvency, creditor rights, debt workouts, bankruptcy, taxes, entity structure, material contracts, regulated obligations, employment law, or financing terms you do not fully understand. Operational strategy should not be used as a substitute for professional legal or financial advice.
How do I know if the restructuring worked?
Measure the business consequence the restructure was meant to change, then use leading signals to explain movement. Depending on the problem, that could be cash generation, contribution margin, retained revenue, delivery capacity, fulfilled orders, cycle time, qualified pipeline, customer retention, or time removed from a manual process. Add a constraint check so improvement in one metric does not simply export cost or risk somewhere else.
Make the new operating model earn its keep
The purpose of crisis recovery is not to prove the company can survive one terrible season. It is to learn what the crisis exposed and decide which assumptions deserve to survive with it.
Secure enough runway to think. Diagnose the constraint. Protect the capability customers still value. Make explicit tradeoffs. Validate the economics. Sequence the transition. Then keep reviewing the evidence, because restructuring is not a ceremony you complete once; it is a set of choices that have to work in the business that actually exists now.
If the symptoms are obvious but the binding constraint is not, contact Scope Design. We can help map the business system, separate the requested tactic from the actual problem, and build a practical decision roadmap before you fund the wrong first move.